Confidential · Professional & Well-Informed Investors Only · A Bittrees Venture · June 2026
A Portuguese real-estate portfolio, anchored by a reserve that is never sold.
BBRF-PT raises institutional capital to build a long-horizon, euro-denominated Portuguese real-estate portfolio without liquidating a core Bitcoin reserve. Investors hold a familiar, senior instrument — convertible preferred shares of a Luxembourg holding company — with a liquidation preference and a preferred dividend.
€25–100MTarget raise
€50,000Minimum ticket
~8% PIKPreferred dividend
1×Liquidation pref.
€11MPilot asset
Important notice. This page is provided for information only to professional and well-informed investors. It is not a prospectus, an offer, or a solicitation, and does not constitute investment, legal, or tax advice. Figures are indicative and subject to definitive documentation and formal legal and tax opinions in Luxembourg and Portugal. Capital is at risk, including total loss.
The Investment Thesis
Three reinforcing positions. One structure.
A ten-year macro position built on three legs. Each hedges and amplifies the others; the structure makes every step transparent enough for institutional investors to underwrite.
Reserve Asset · Never Sold
Long Bitcoin
The hardest monetary asset yet created. Its continued monetisation is credible over a ten-year horizon. Across sustained four-year cycles Bitcoin has historically appreciated on the order of 40–60% per annum — historical, not a forecast. The principal risk is regulatory, not structural.
Historical cycle appreciation 40–60% p.a.
Currency Hedge · Euro-Denominated
Hedge the dollar
With roughly $39 trillion of US federal debt and ~$1 trillion a quarter in interest, the long-run path of least resistance is currency debasement rather than collapse. Euro-denominated hard assets provide structural protection; borrowing dollars at a low, regulated cost against a Bitcoin reserve converts that thesis into a financeable position.
Debasement, not collapse
Hard Asset · Income-Producing
Long Portugal
Lisbon at roughly €5,000–6,000/m² remains well below Paris (€10,000–12,000) and comparable to Barcelona, with mature tourism infrastructure, supply constrained by licensing, and durable inbound demand. Euro-denominated and income-producing.
Net rental yields 3–5%
The structural alpha is in not selling the Bitcoin.
The reserve is posted as collateral through regulated channels to borrow conservatively at an indicative ~2–5% per annum; the borrowed euros acquire income-producing Portuguese real estate; rental income services the borrowing and funds distributions. The claim is not "free leverage" — the borrowing cost is real and included in every illustration. Conservative loan-to-value is maintained at all times, with collateral health monitored continuously and defined de-risking actions.
The Currency Hedge, Quantified — Illustrative
A €12M loan in a depreciating currency.
Nominal loan outstanding vs its real purchasing-power value at −7%/yr dollar debasement · Illustrative · Not a forecast
Structure & Instrument
A corporate structure, not a token scheme.
Investors hold a senior, familiar security issued by BBRF-PT Holding S.A., a Luxembourg SOPARFI. The on-chain transparency layer (tokenised share register, published governance records, bbrf-pt.eth) is a reporting feature — it does not alter the legal rights of the shares. The Bitcoin reserve is held in regulated institutional custody, multisig from inception, never on exchange.
~8% per annum, cumulative, accruing (PIK) until conversion or liquidity event
Valuation
€100M pre-money (indicative) — priced now, not via cap/discount
Conversion
1:1 into common at a qualified financing, sale, or listing; holder receives the greater of conversion value or liquidation preference
Investor rights
Pro-rata participation, information rights, protective consents on major matters
Liquidity
12-month lock-up → quarterly redemptions up to ~10% of pool → secondary transfers from Year 2 → wind-down available from Year 8
Operations
Portuguese operating company; one SPV (Sociedade Unipessoal, Lda.) per asset for ring-fencing and disposal optionality
Eligibility
Professional and well-informed investors only · Luxembourg private placement
Five functions permanently independent.
Independent auditor, independent valuation, smart-contract audit, regulated custody, and fund administration remain external and bound by mandate at all times — none is performed by the operating company or the principals.
Pilot Acquisition
Pebble Stone Farm — the proof of concept.
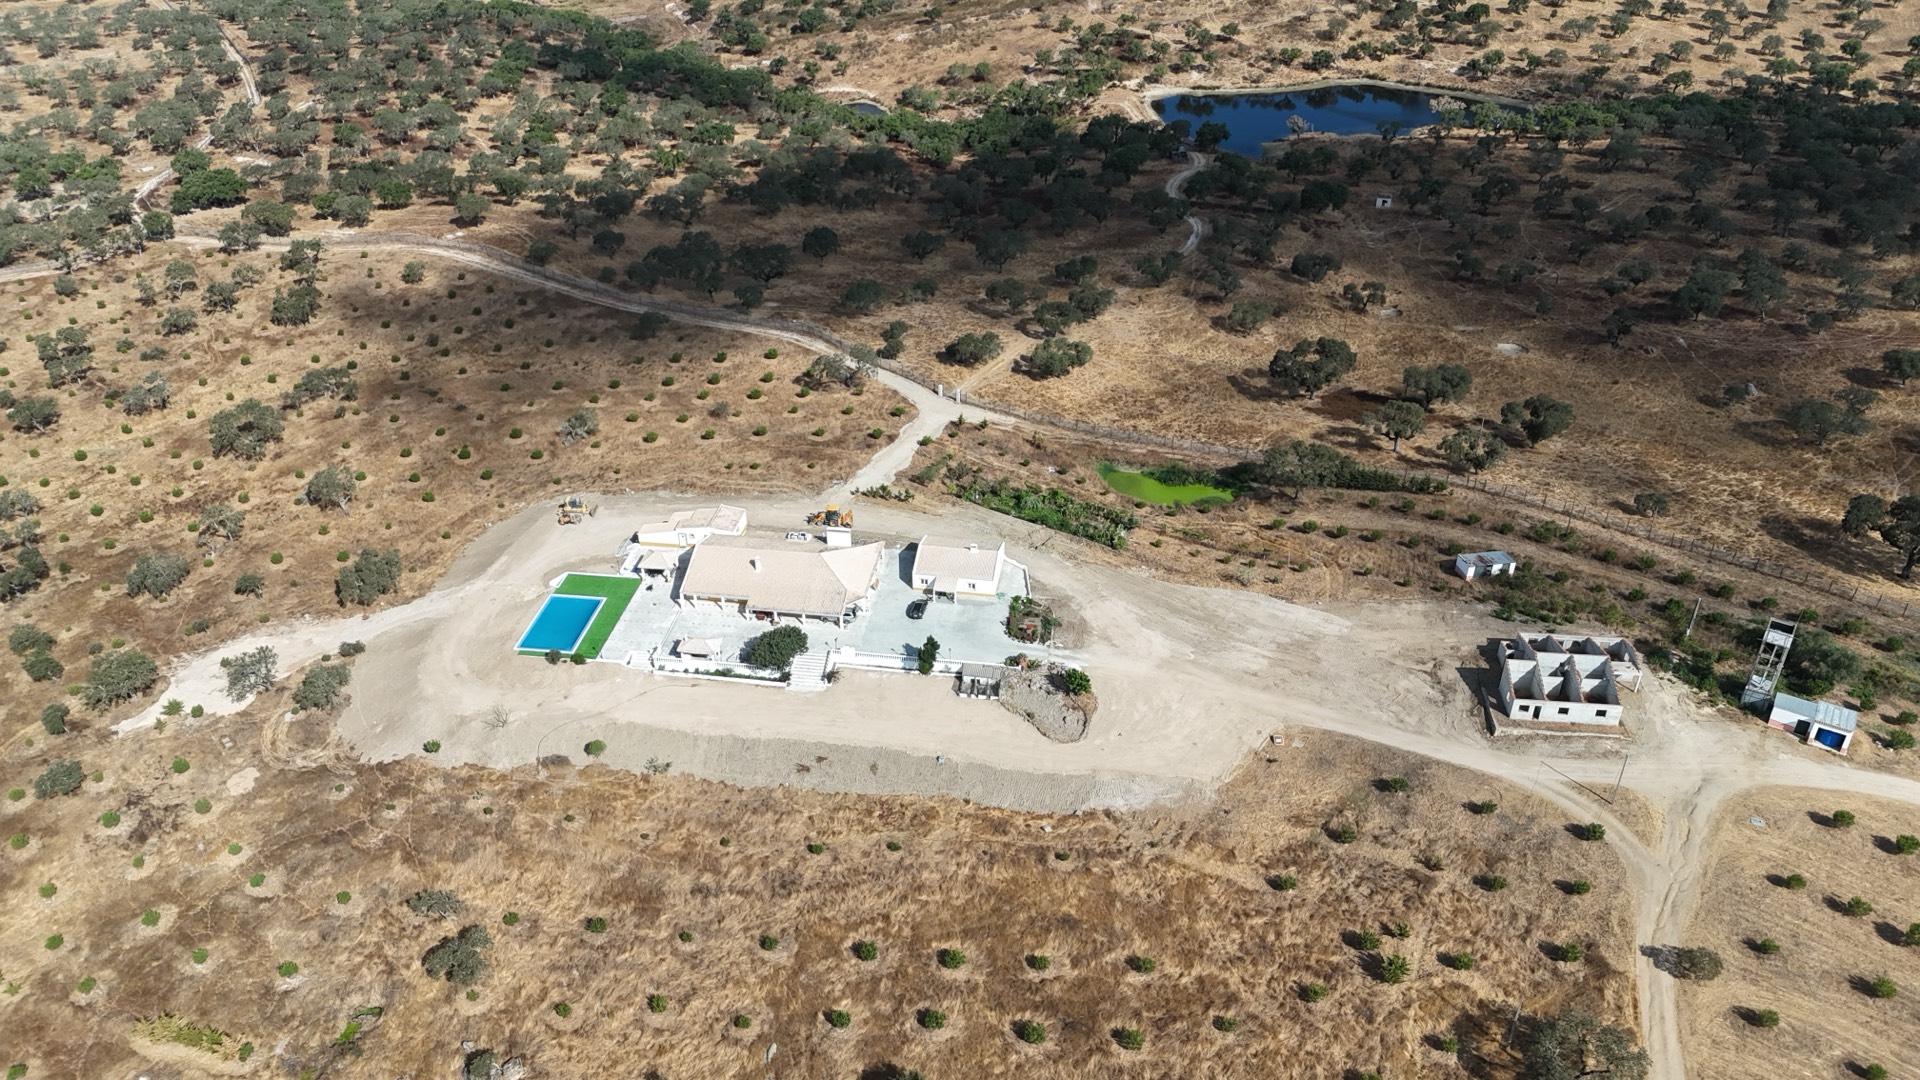
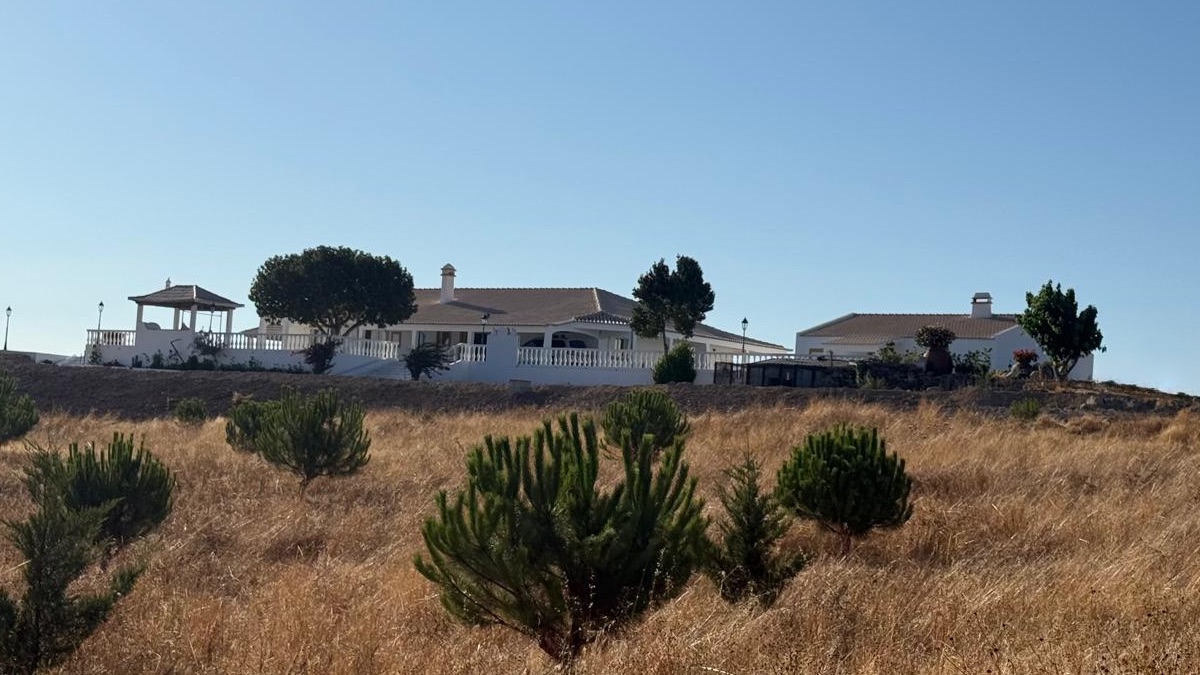
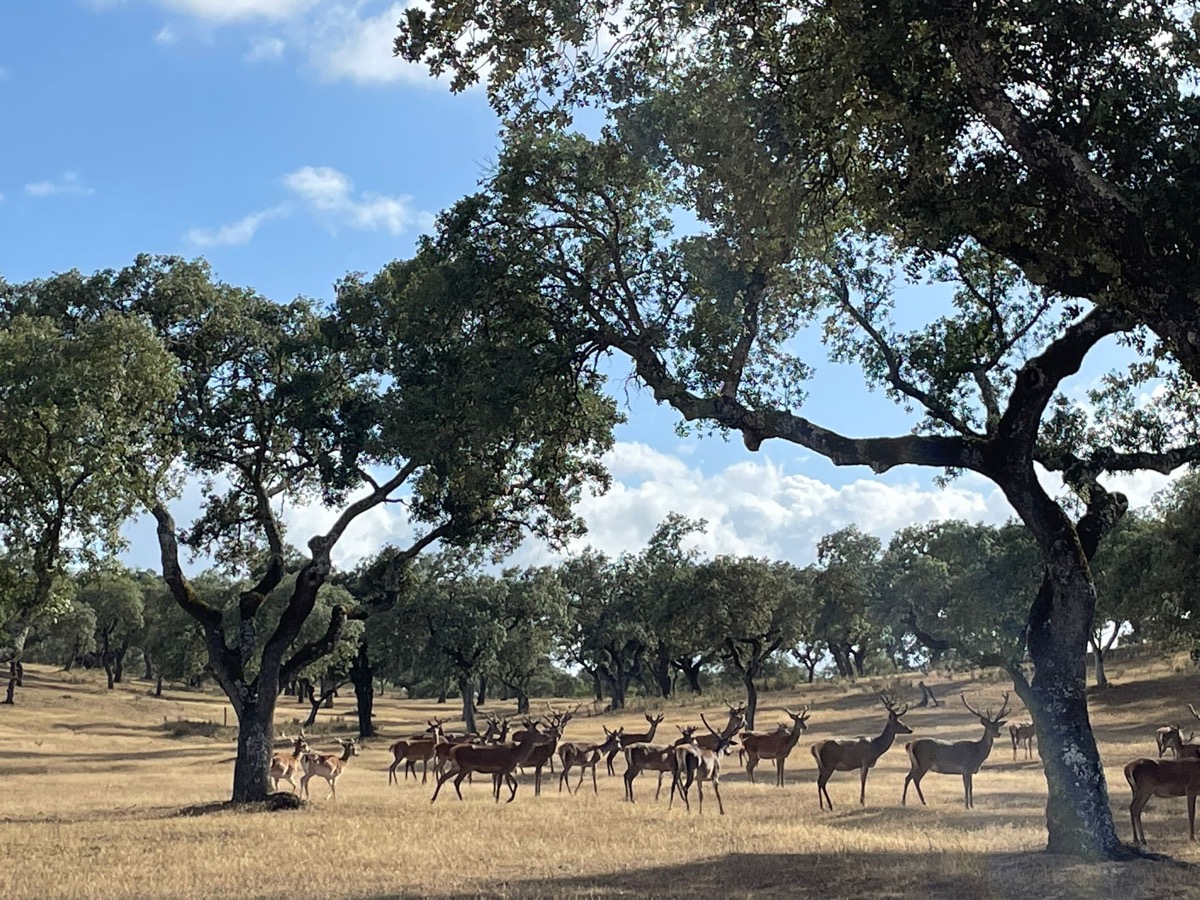
The first acquisition is identified, not hypothetical: a ~€11M, 1,000-hectare hunting estate in Portugal's Alentejo. One SPV through which the full legal, custody, governance, and yield mechanics are proven end-to-end before the institutional raise opens.
Asset
1,000 hectares
Institutional scale, off-market access, single-title simplicity, in Portugal's premier hunting and agricultural region.
Income
Multiple streams
Hunting-estate operations, agricultural revenue, and future hospitality optionality — a specialty asset class aligned to the long-horizon thesis.
Role
Full-stack proof
Legal, custody, lending, governance, and yield mechanics proven end-to-end at a manageable scale before institutional capital is accepted.
Returns are driven by Bitcoin appreciation on the reserve, Portuguese real-estate appreciation, and rental yield. Borrowing cost (~2–5% p.a.) is netted against acquisition leverage. Illustrative only — not forecasts; capital is at risk.
Conservative
~€2.8M
BTC ×6 · RE ×1.8 · 10 years
Base
~€6.0M
BTC ×10 · RE ×2.3 · 10 years
Upside
~€9.5M
BTC ×15 · RE ×2.8 · 10 years
The Spread, Visualised — Illustrative
Historical appreciation vs the cost of capital.
Indexed to 1× at Year 0 · Conservative 30% CAGR shown against a ~3.5% APR borrowing cost · Illustrative · Not a forecast
Risk & Stress Testing
Every leg carries real risk. All of it is disclosed.
A full quantitative stress-test framework is built and disclosed before any capital is drawn. Each category receives a Monte Carlo simulation and a deterministic worst-case scenario; the output is a concise risk addendum delivered to every investor before commitment — a precondition for institutional capital, not an option.
Market
Bitcoin drawdowns at −50% / −70% / −85% modelled against collateral LTV; combined stress (BTC −70% + Portugal RE flat three years + EUR/USD −15%); cascade and recovery-path analysis.
Operational
Custody breach, multisig key compromise, lending-counterparty failure, oracle/valuation error, smart-contract exploit — each with a defined response, insurance cover where available, and a recovery protocol.
Regulatory
Changes to Luxembourg or Portuguese rules, securities reclassification, banking de-risking of euro rails — mitigated by conservative structuring, fallback arrangements, and a clean wind-down.
Liquidity & Counterparty
Lender concentration diversified across regulated counterparties; redemption pressure managed by the lock-up and capped windows; asset-level liquidity managed at SPV level.
Fees & Tax Structure (Indicative)
Every cost, on the table.
Full fee schedule and first-pass tax design — to be validated by formal opinion from VdA or Morais Leitão (Portugal) and Arendt & Medernach or Loyens & Loeff (Luxembourg) before first close. Not tax advice.
21% IRC on net rental income; IMT 6–8%; stamp 0.8%; IMI ~0.3–0.45%
SPV → holdco
Generally exempt under EU Parent-Subsidiary Directive
Bitcoin reserve
Held at holdco in regulated custody; treatment confirmed by opinion
Distributions
EUR/EURC — generally no Luxembourg withholding for non-residents
Carry / fees
At Luxembourg level; deal fees expensed at SPV level
Capital Raise & Distribution
€25M minimum. €100M full vision.
Below €25M, fixed overhead exceeds the structural alpha. The raise is led from Luxembourg with a licensed placement agent (1–2% success fee) and a disciplined calendar: 3–5 anchor commitments of €2–5M secured first, roughly 150 qualified conversations at 20–30% conversion, 6–9 months from first to final close.
Reserve vs deployment per €1M committed · Ratio policy finalised at formation
■ Bitcoin reserve — never sold, regulated custody ■ Real estate — leveraged ~2–3× via the reserve
Portfolio Value at Scale — Illustrative
Ten-year trajectory by raise tier.
Reserve compounding + leveraged appreciation + yield reinvestment · Not a forecast
Open items before formation — disclosed, none blocking.
Share classes and conversion mechanics; custody and lending counterparties; on-chain layer scope; advisory selection; BTC/RE ratio policy. Roadmap: legal & entity → custody & leverage → pilot → distribution.
The Sponsor & Team
Two principals. An independent bench.
Real Estate · Multi-Jurisdictional
Eytan Benzeno
Lisbon-based real-estate principal; Florida broker licence; operating across Portugal, Israel, Luxembourg, and the US. Multi-asset experience across residential, hospitality, distressed, and agricultural. Co-founder of Bogen.ai. Multilingual.
On-Chain Structuring & Operations · Bittrees
Jonathan Hineline
On-chain governance and operations architect. Designs the reserve-and-leverage mechanics, the tokenised share register, and the transparency layer. Deep network of smart-contract auditors and infrastructure engineers.
The conversation starts with the memorandum.
We are speaking with a small number of anchor investors and formation partners. Request the full investor memorandum, or schedule a call with the principals.